Time for Big Mac – The Market Access Charge
Yes, it is time for the United States to adopt the Big Mac. No, it’s not the burger. It is the Market Access Charge (MAC) that former Bell South Economist John Hansen has been urging the U.S. government to adopt as a way of reducing over-valuation of the U.S. dollar, the U.S. trade deficit, and […]
Markets Swinging
This past week has seen markets swinging between negative and positive territory on news of a potentially escalating war in Ukraine, continuing talks of an incoming recession, and the largest increase in core inflation in 40 years. The core CPI (Consumer Price Index that excludes food and energy) climbed 6.6% in September, showing that inflation has spread across the economy, and supporting expectations of further Fed tightening in the November FOMC meeting. Although the market initially dropped on the news, on Thursday, it ended up closing strong. On Friday, banks posted their latest results, showing resilience even in the current economic environment. JPMorgan beat expectations, though it set aside hundreds of millions of dollars preparing for the recession that CEO Jamie Dimon has been calling for months. The week ahead will be one of the busiest corporate earnings seasons, with Bank of America, Goldman Sachs, Netflix, Tesla, and others, scheduled to report their most recent results.
Americans Held Hostage – Incorporated in America but Commanded by China
On December 2, 2015 a terrorist attack took place on a training event of the Department of Public Health at the Inland Regional Center of San Bernardino, California. Of the eighty people attending, fourteen were killed and twenty two were seriously injured. As chance would have it, the shooters dropped an iPhone which was picked […]
OPEC+ Cut Sends Indexes Down
The market fell in the second half of the week, following two consecutive strong days to kick off the last quarter of the year. The OPEC+ decision to cut oil production by 2,000,000 barrels daily on Wednesday renewed concerns of raising inflation in Europe and the US, sending major indexes down and energy prices up. Then Friday’s strong employment report sent the market further down as investors brace for further Fed tightening. The coming week’s focus will be on (guess what?) inflation. On Wednesday, the Bureau of Labor Statistics (BLS) will release the Producer Price Index (PPI), which will show if production, transportation, and storage costs are finally trending down after the Fed’s aggressive tightening of the past quarter. On Thursday, the Consumer Price Index (CPI) will also provide an updated view of the effects of the Fed’s economic policy. Consumer prices are projected to have increased 0.2% last month, compared with a 0.1% gain in August and a flat reading in July. On Friday, Retail sales will tell if consumers’ demand has also been slowed down by increased borrowing and living costs.
September Effect Resurfaces

History repeats with the ghost of the September Effect resurfacing as the worst-performing month on average. This is the worst September since 2002, with the S&P 500 declining 9.21%, culminating in the YTD return to –23.87%. What might surprise the average investor is bonds, represented by the Barclay US Aggregate and Long Treasuries YTD, have also posted losses of -14.61% and -28.84%, respectively. The market attempted to find its footing early in the week from the prior week’s decline. Still, it was subdued by recession fears with a rise in wholesale inventories, a slowdown of the housing market, and the Fed’s unwavering rate hike of three-quarters of a percentage point. History has shown that investors’ emotional tendencies often impact rational decision-making during stressed markets. If history repeats, the October Effect ahead tends to be net positive months. The coming week is filled with third-quarter key economic releases, including factory orders, jobs, and the state of the consumer. Critically more important in the weeks ahead are third-quarter company earnings releases and their forward guidance heading into 2023.
Markets Rocked by Fed Message
Markets were rocked by the Fed’s message “will keep at it until the job is done,” referencing the commitment to returning inflation to its 2% objective. As a result, the S&P 500 posted a loss of -4.63% bringing the YTD loss to -21.61%. Bond markets also declined by -1.56% bringing the YTD loss to -13.75% (while Long-term Treasuries have declined by -26.80% YTD). There is visible weakness in the U.S. economy with a slowing in the housing market and the Leading Index posting a -0.3%; however, the jobs market with lower jobless claims and improving retail and manufacturing continuing to post positive results as a headwind to the Fed’s effort to fight inflation. With housing prices falling by approximately 6% this year and equity markets declining by 20%, the wealth of U.S. households is definitely taking a hit and may eventually trickle down to lower demand.
The coming week will be filled with another week of headlines, with Fed Chair Powell speaking on Wednesday, followed by the release of critical housing data, GDP, and wholesale inventories.
Green Danger Ahead?
With the Inflation Reduction Act and the European Climate Law, the West is pushing to exit oil and natural gas to prevent severe climate change and reduce dependence on foreign suppliers. As a result of the new laws and economic incentives, electric vehicle (EV) sales are expected to dominate the car market for the years to come. And the battery industry will grow along with it. Common lithium-ion batteries in use nowadays are made of various combinations of metals that include Lithium, Cobalt, and Copper: Lithium is mainly extracted from underground ponds in Australia, Chile, China, and Argentina. The process is very water-expensive and often causes damage to the land and trouble to the local communities; Cobalt is mainly extracted in the Democratic Republic of Congo (DRC), which supplies about 70% of global production. Unlike mines in developed nations, where heavy machines accelerate operations and safeguard workers, human hands dig up much of the cobalt. Often children’s hands. Mining and refining metal is an energy-intensive business, and the energy used often comes from coal and other fossil fuels. Therefore, the push to quickly abandon fossil fuels brings several hidden costs.
ECB Raises Key Rate 0.75 Points
The EURUSD wavered around parity for most of the week and recovered some ground on Friday after the ECB (European Central Bank) decision to raise its key interest rate by 0.75 points. Over the years, heavy reliance on cheap Russian gas has exposed the nations in the Euro area to wide energy cost swings. The spike in prices in the past year has hit households and businesses across the continent with unbearable utility bills that were quickly followed by a general increase in goods prices (as businesses adjusted to larger production costs). Both Demand and Sentiment have been suffering as a result, as highlighted by McKinsey [https://www.mckinsey.com/business-functions/growth-marketing-and-sales/our-insights/survey-european-consumer-sentiment-during-the-coronavirus-crisis]. In its July survey, more than a third of respondents reported spending on nonfood discretionary items decreased due to the pricing pressure. And consumption could fall even more in the winter, as energy takes an even larger portion of consumers’ budgets.
DYNAMIC DUOS 2022: Cindy and Bill Sowell
Global Supply Chain Issues Down
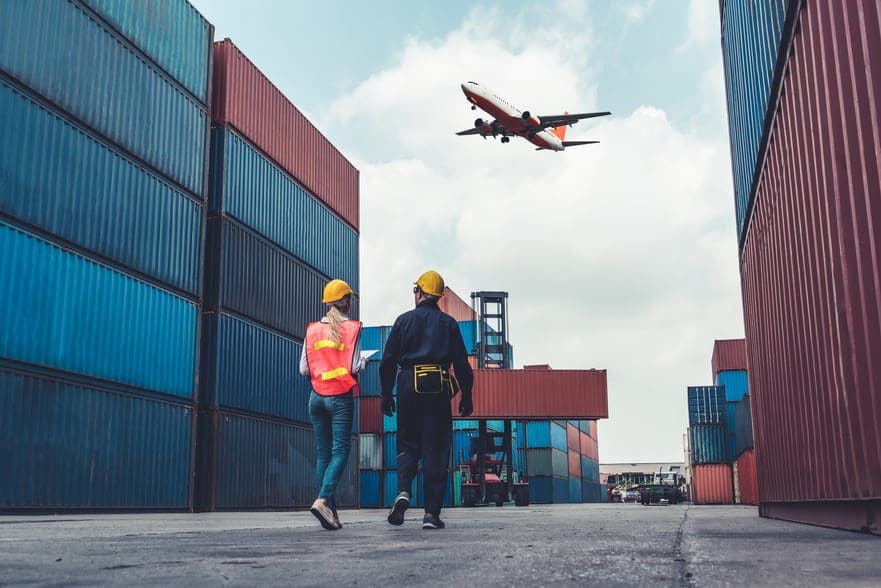
Shifts in demand, labor shortages, and lockdowns that began in 2020 with the worldwide spread of Covid-19 are some of the main drivers of the global supply chain crunch that has largely affected the prices of goods and services in the past two years. The invasion of Ukraine in 2022 and its geopolitical consequences have added more stress to an already chaotic situation. Decreasing demand for new products due to high prices and borrowing rates, and relaxation of the strict covid rules that have disrupted the supply chain for months, could be enough to lower the inflationary pressure in the next year. According to the Oxford Economics supply chain tracker, the situation has been improving over the past few months, and supply-chain conditions in the U.S. offered encouraging signs to start Q3. Cargo ship backlogs in Southern California have declined for six straight months now, and other modes of transport also signaled reduced stress. Shipping prices were flat or fell, as well. Though Ukraine War adds uncertainty to the mix, making it hard to predict when the supply chain issues will resolve, there are signs that the situation is improving and demand and supply are slowly converging towards an equilibrium.